Flow-through tax advantage
A MIC deducts the dividends it pays, so income is taxed once — in your hands. Held in an RRSP, RRIF or TFSA, distributions can compound on a tax-sheltered basis.
DX Financial (Canada) Ltd. · Exempt Market
A Mortgage Investment Corporation flows through virtually all of its income to investors — delivering risk-adjusted monthly income secured by real property in the Greater Toronto Area.
Available to eligible and accredited investors under prospectus exemptions.
60-second introduction from Leo, Dealing Representative
How it works
The Government of Canada introduced MICs in 1973, through the Residential Mortgage Financing Act, to make it easier for individual and corporate investors to participate in the residential mortgage and real estate markets.
Investors pool their money by buying shares of a MIC. The pooled capital funds mortgages, which generate income through interest and fees from the borrower that are ultimately paid out as dividends to each investor. The structure is defined under Section 130.1 of the Income Tax Act.
Capital is pooled from individual, corporate and registered-plan investors.
The MIC lends the pool out as mortgages registered against real property.
Interest and fees collected each month form the income of the corporation.
Virtually all income is distributed to shareholders as dividends.
A MIC deducts the dividends it pays, so income is taxed once — in your hands. Held in an RRSP, RRIF or TFSA, distributions can compound on a tax-sheltered basis.
Every loan is registered against real property with conservative loan-to-value limits, so capital sits behind tangible security rather than market sentiment.
Borrowers pay interest monthly. That interest funds regular distributions with far less day-to-day volatility than publicly traded equities.
Diversification across many mortgages, disciplined underwriting and active portfolio monitoring are designed to protect principal first.
Why invest in a MIC
Risk exposure is mitigated by spreading the investment across a portfolio of mortgages rather than a single mortgage.
A MIC provides short-term loans secured by real estate properties, so capital sits behind tangible collateral.
A MIC is eligible for investment from registered funds such as RRSP, RESP and TFSA, allowing the investment to grow tax-efficiently.
A steady stream of income is provided to investors while the investments remain secured by real property.
Individuals can participate in larger investments by combining their capital with other investors.
Why DX Financial
The MIC is managed by a team with over a decade of hands-on experience in the Canadian mortgage industry.
The mortgage portfolio consists mostly of residential properties in highly coveted locations within the Greater Toronto Area.
The management team follows a well-defined risk mitigation protocol and underwriting system on every mortgage.
Respected as a leading law firm, Fasken provides securities counsel to ensure best operational practices.
The manager of the MIC is also a significant investor in it — co-investing motivates prudent decisions and strong returns.
Auditing by Licensed Public Accountants ensures comprehensive and transparent financial reporting.
About Leo
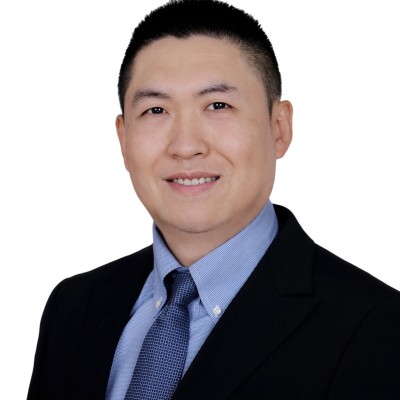
Leo began his career in audit and advisory at PwC in Beijing, where he built the analytical rigour and controls mindset that still shapes how he evaluates investments today.
He went on to insurance asset management, overseeing fixed-income and income-generating mandates where capital preservation and predictable cash flow mattered more than chasing returns.
Today, as an OSC-registered Dealing Representative with DX Financial (Canada) Ltd., he helps Canadian investors and their advisors understand where private mortgage investing fits in a portfolio — and, just as importantly, when it does not. He holds an MBA and the CIA designation, with more than 20 years of experience across accounting, asset management and private credit.
Have a question?
Share a few details and Leo will send the investor package and arrange a no-obligation call to review your objectives, time horizon and eligibility.